
After economic activity came in weaker than expected in the second quarter, Brazil’s Finance Ministry cut its forecast for gross domestic product growth in 2026. The ministry now expects the economy to expand 2% this year, down from its previous forecast of 2.3% made in July. For 2027, the growth forecast was lowered to 2.3% from 2.5%.
The latest forecasts were released Tuesday (22) by the Economic Policy Secretariat (SPE) in its Macrofiscal Bulletin, which updates the government’s macroeconomic assumptions. The new figures will underpin the release of the government’s bimonthly report on budget revenue and spending, due Thursday (24).
The downgrade to the 2026 GDP forecast was driven by lower projections for the services and industrial sectors. The ministry cut its forecast for services growth this year to 1.8% from 2.4% and for industry to 1.7% from 2.1%. These revisions were “partially offset” by agriculture, for which the growth forecast was raised to 2.8% from 1.8%.
For the SPE, although household debt remains stable as a share of income, “debt-service burdens reached their highest level in the historical series in the second quarter, limiting the extent to which household income growth can translate into consumption.”
In the industrial sector, the downgrade reflects weaker performance in manufacturing, which remains under pressure from high borrowing costs and softer demand for consumer goods, while extractive industries continue to support the sector.
For the third quarter, the Finance Ministry expects GDP to grow 1.8% from a year earlier, down from 2% in the second quarter. The slowdown is being driven by agriculture and, to a lesser extent, industry.
In the final quarter of the year, the government expects GDP growth to accelerate again to 2.1% year over year as the effects of the Selic policy interest rate cuts, which began in March, gradually feed through to the economy. The benchmark rate currently stands at 13.75% a year.
For 2027 GDP, the SPE said the downward revision to economic growth was influenced by the lagged effects of Selic rate transmission through the economy.
The GDP revisions are based on a scenario in which average Brent crude prices remain elevated due to the Middle East conflict. For 2027, however, prices are expected to stabilize over time, although at a higher level than previously projected. Between the July and September sets of macroeconomic assumptions, the average Brent price forecast for 2026 rose to $87.70 a barrel from $79.20. For 2027, the forecast increased to $79.50 from $71.
On inflation, the Finance Ministry lowered its forecast for the Extended Consumer Price Index (IPCA) to 4.9% in 2026 from 5.1%. The forecast remains above the 3% inflation target and its 4.5% upper limit. The ministry now expects the National Consumer Price Index (INPC) to rise 5.1% this year, down from its previous forecast of 5.3%.
According to the SPE, the downward revision to the 2026 IPCA forecast reflects inflation data through July, particularly weaker-than-expected food prices. The revision also reflects improved inflation expectations for 2026, the Selic rate remaining at a restrictive level despite the start of monetary easing, and a slowdown in economic activity in the second half of the year.
The forecast, however, does not consider recent measures to subsidize and cut taxes on fuels. The figures were finalized on September 4, before the government announced an extension of fuel subsidies due to the prolonged conflict in the Middle East. Government experts estimate that tax cuts on gasoline and hydrous ethanol, excluding the diesel subsidy, could reduce IPCA inflation by about 0.15 percentage point in 2026.
For 2027, the IPCA forecast was raised to 3.8% from 3.6%. The INPC forecast was also raised, to 3.9% from 3.7%. The marginal upward revisions reflect the stronger El Niño effects on next year’s harvest, as well as a fertilizer shock.
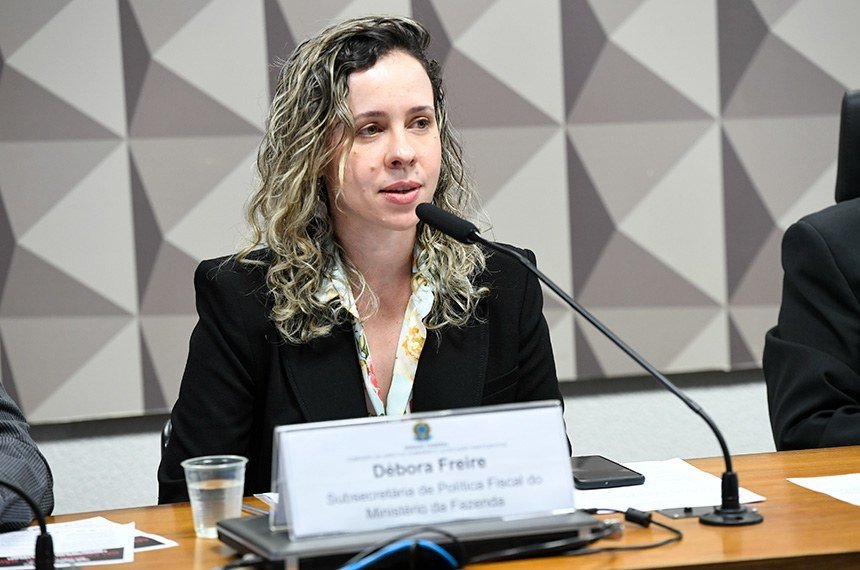
Regarding the 15% increase in the Bolsa Família income-transfer program, Economic Policy Secretary Débora Freire said the measure will have a positive impact on economic activity in 2027, although the effect is likely to be tempered by the economic slowdown and the effects of monetary policy.
“The increase in Bolsa Família benefits is likely to contribute positively to economic activity, but it is a welcome factor given this slowdown scenario, and it does not conflict with monetary policy because we are in a monetary-easing cycle,” Freire said.
The effects of the Bolsa Família increase were not incorporated into the forecasts because the measure was announced after the macroeconomic assumptions had been finalized.
